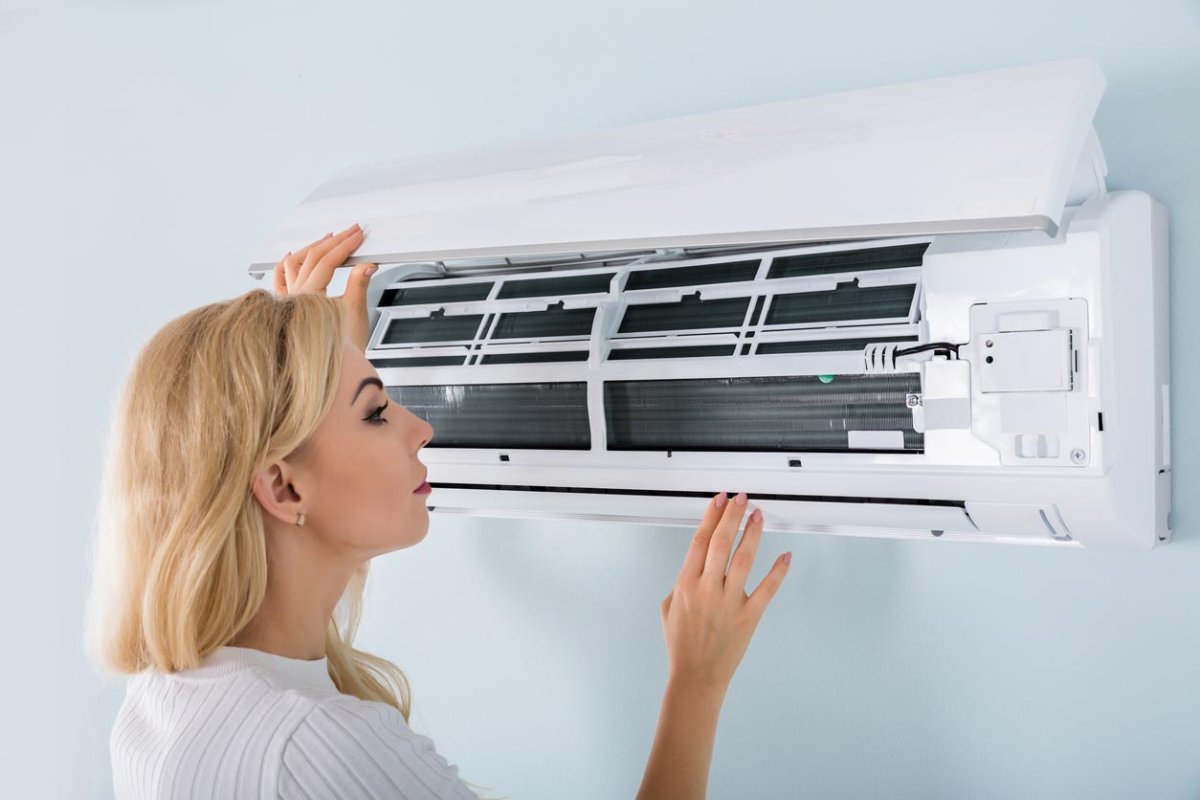
Few household sounds are more unsettling than an air conditioner making one heroic clunk and then going silent during the hottest week of the year. After checking the thermostat, flipping the breaker, and whispering motivational words at the outdoor unit, many homeowners ask the expensive question: “Will my home insurance pay for this?”
The honest answer is sometimesbut only when the air conditioner was damaged by a cause covered under your policy. Homeowners insurance is designed primarily for sudden, accidental losses caused by covered events. It is not normally a maintenance plan for equipment that becomes old, inefficient, rusty, or simply tired of participating in summer.
Getting an air conditioner covered therefore depends less on how uncomfortable your living room feels and more on what caused the damage, how your system is classified, what endorsements you purchased, and how well you document the claim. Here is how to approach the process accurately, legally, and strategically.
When Does Homeowners Insurance Cover an Air Conditioner?
A standard homeowners policy may help repair or replace an air-conditioning system when a covered peril directly causes the damage. The exact list appears in your policy, but common covered events may include fire, lightning, wind, hail, vandalism, theft, explosions, and falling objects.
The phrase directly causes matters. Your insurer will investigate whether the event actually damaged the unit or merely happened around the same time that an aging compressor failed.
Storm, Wind, and Hail Damage
Suppose a severe thunderstorm sends a tree limb crashing into the outdoor condenser. The impact bends the fan assembly, punctures the coil, and leaves visible debris around the unit. Because wind and falling objects are commonly covered perils, the resulting damage may qualify under dwelling coverage, subject to your deductible and policy limits.
Hail can also damage condenser coils, fan blades, and metal housing. A successful claim is more likely when photographs, local storm records, an HVAC inspection, and the physical condition of the unit all support the same timeline.
Lightning and Certain Power-Surge Losses
A direct lightning strike may destroy an AC control board, motor, compressor, thermostat, or connected electrical components. Lightning damage is generally covered by standard homeowners insurance, and some policies also cover a power surge resulting directly from lightning. Coverage for other utility-related surges may depend on the wording of the policy or an equipment breakdown endorsement.
Because electrical failures are not always visible, ask a licensed HVAC technician or electrician to identify the failed components and explain whether the damage is consistent with a sudden surge rather than deterioration.
Fire, Smoke, and Vandalism
If a covered house fire damages the HVAC system, insurance may pay for necessary repairs or replacement as part of the broader property claim. The same may apply when vandals intentionally damage an outdoor condenser or thieves steal covered components.
Promptly report theft or vandalism to law enforcement, preserve the incident number, and photograph disturbed wiring, broken panels, tool marks, or missing parts. Do not clean up the scene so enthusiastically that the evidence disappears before the insurer sees it.
Water and Freezing Damage
Some policies cover sudden and accidental water damage or the freezing of plumbing, heating, and air-conditioning systems. Gradual leaks, neglected drainage problems, groundwater, and ordinary flooding are generally treated differently. Standard homeowners insurance normally excludes flood damage, which usually requires separate flood coverage.
For example, a sudden burst pipe that damages an indoor air handler may produce a covered claim. A condensate drain that has leaked unnoticed for eight months is much more likely to be considered a maintenance problem.
When Home Insurance Probably Will Not Pay
Homeowners insurance generally does not cover an air conditioner that fails because of normal wear and tear, old age, corrosion, poor maintenance, misuse, improper installation, a manufacturer defect, or gradual deterioration. Those problems are considered predictable ownership expenses rather than sudden insured losses.
A 17-year-old compressor that stops working on a hot afternoon has not necessarily suffered an insurable loss. It may simply have reached the mechanical equivalent of retirement age.
Coverage may also be denied when:
- The repair cost is lower than the policy deductible.
- The damaging event is specifically excluded.
- The homeowner failed to prevent additional damage after discovering the problem.
- Permanent repairs destroyed evidence before inspection.
- The claimed damage existed before the policy began.
- The technician cannot connect the failure to a covered event.
- The policyholder provides inaccurate or contradictory information.
Central AC Versus Window Units
How the air conditioner is installed may determine which section of your policy applies. A central AC system or permanently installed compressor is usually considered part of the dwelling. A removable window or portable air conditioner is more likely to fall under personal property coverage.
This distinction can affect coverage limits, deductibles, depreciation, and settlement calculations. It may also determine whether the insurer pays replacement cost or actual cash value. Check both the dwelling and personal-property sections instead of assuming every cooling device is treated the same way.
How to File an Air-Conditioner Insurance Claim
1. Identify What Happened Before Filing
Do not begin with, “My AC is broken, and I would like a new one.” Begin by investigating the event. Was there lightning, hail, fire, vandalism, a fallen object, or a sudden water incident? When did the system last operate correctly? Did lights flicker? Did a breaker trip? Did neighbors experience similar surge damage?
You do not need to become an amateur claims detective wearing sunglasses indoors, but you should establish a truthful and consistent timeline.
2. Review Your Policy and Deductible
Read the declarations page, coverage form, exclusions, endorsements, and deductible provisions. Look for terms such as:
- Dwelling coverage
- Personal property coverage
- Covered causes of loss
- Mechanical breakdown exclusion
- Electrical current or power-surge coverage
- Equipment breakdown endorsement
- Replacement cost
- Actual cash value
Then compare the likely covered loss with your deductible. The National Association of Insurance Commissioners recommends checking the deductible before filing because a relatively small loss may cost less to repair out of pocket.
For example, imagine a storm causes $2,300 in covered AC damage and your deductible is $2,500. Even if the event qualifies, there may be no claim payment. If covered damage totals $8,000 with a $1,500 deductible, pursuing the claim makes considerably more financial sense.
3. Document Everything Before Moving or Repairing It
Take wide-angle and close-up photographs of the air conditioner, nearby property, electrical panels, damaged wiring, hail dents, debris, water marks, burned components, and anything else relevant to the event. Record videos showing unusual sounds, error messages, leaking water, or a nonfunctioning fan.
Save weather alerts, utility notices, fire reports, police reports, equipment manuals, installation invoices, prior maintenance records, and older photographs showing the unit’s pre-loss condition. Consumer and insurance authorities consistently recommend photographs, receipts, inventories, and written estimates when supporting a property claim.
4. Prevent Additional Damage
Policyholders are generally expected to take reasonable steps to stop a loss from becoming worse. You might shut off electricity to an unsafe unit, cover an exposed opening, remove standing water, or arrange a temporary emergency repair.
Keep receipts and photograph the condition before and after temporary work. Avoid permanent replacement until the insurer has inspected the system or authorized you to proceed. Making irreversible repairs too soon can complicate the investigation and may jeopardize coverage when the original damage can no longer be examined.
5. Obtain a Detailed HVAC Diagnosis
A one-line invoice stating “AC deadreplace unit” is not especially persuasive. Ask a licensed technician for a written report that includes:
- The manufacturer, model, serial number, and approximate age
- The components tested
- The specific components that failed
- The probable cause of the failure
- Whether the failure was sudden or gradual
- Evidence of impact, electrical, fire, water, or storm damage
- Whether repair is technically possible
- Itemized repair and replacement estimates
- Any required code-related work
Ask the technician to separate damage caused by the covered event from unrelated maintenance or preexisting deterioration. That distinction helps the adjuster understand exactly what portion of the bill belongs in the claim.
6. Report the Claim Promptly and Accurately
Contact the insurer or agent as soon as reasonably possible. Reporting deadlines vary by policy and state, so procrastination is not a useful negotiating technique. Provide the date of loss, cause, location, known damage, emergency measures, and contact information for your contractor.
Describe facts, not guesses. It is appropriate to say, “The technician found electrical damage consistent with the surge that occurred during the July 10 storm.” It is not appropriate to invent lightning damage because the compressor failed during a week when the forecast included clouds.
Knowingly submitting false, incomplete, or misleading claim information may constitute insurance fraud and can result in claim denial, fines, civil liability, or criminal penalties.
7. Prepare for the Adjuster’s Inspection
Create a single organized claim file containing photographs, videos, the HVAC report, estimates, receipts, maintenance history, weather evidence, and a written timeline. Provide copies to the adjuster and keep the originals.
Attend the inspection when possible. Point out damage without exaggerating it, and ask whether the adjuster needs additional testing or documentation. Afterward, send a short email summarizing what was inspected and any follow-up items. A written communication trail is more reliable than trying to remember a six-minute phone call three months later.
How Much Will the Insurance Company Pay?
A covered claim does not automatically produce a check equal to the price of the fanciest new HVAC system available. Payment depends on the deductible, coverage limit, settlement method, damaged components, depreciation, policy exclusions, and whether repair or replacement is reasonably necessary.
Replacement Cost Versus Actual Cash Value
Replacement-cost coverage generally pays the covered cost of replacing damaged property with comparable property, subject to policy terms. Actual cash value subtracts depreciation based on age, condition, and useful life. NAIC consumer guidance warns that actual cash value may provide substantially less than the amount needed to purchase a new replacement.
Some insurers initially pay an actual-cash-value amount and release recoverable depreciation after the work is completed and invoices are submitted. Ask the adjuster whether multiple payments will be issued and what documentation is required to recover the remaining amount.
Matching and System Compatibility
An insurer may propose replacing only the component directly damaged, such as the outdoor condenser. Your HVAC contractor may argue that the old indoor coil, refrigerant type, control system, or efficiency rating is incompatible with the proposed replacement.
Request a written technical explanation rather than relying on “the contractor says the whole thing has to go.” The stronger document explains why a partial repair would violate manufacturer requirements, building codes, safety standards, or accepted installation practices.
What Is Equipment Breakdown Coverage?
An equipment breakdown endorsement may fill part of the gap between ordinary homeowners insurance and mechanical failure. Depending on the insurer and policy, it can cover sudden electrical, mechanical, or pressure-system breakdowns affecting HVAC equipment and other home systems. It still generally excludes ordinary wear and tear.
This endorsement can be useful when a compressor motor burns out or a sudden electrical event damages equipment but does not fit neatly within the standard policy’s covered perils. Coverage limits, deductibles, age restrictions, and exclusions vary, so review the actual endorsement before assuming every malfunction qualifies.
Home Warranty Versus Homeowners Insurance
A home warranty is a service contract rather than property insurance. It may help pay for covered HVAC repairs or replacement when parts fail through ordinary use, subject to service fees, coverage caps, exclusions, and provider rules. Homeowners insurance, by contrast, generally responds to covered external events such as fire, theft, or storm damage.
In practical terms, a worn-out blower motor might be a warranty issue, while a condenser crushed by a windblown tree limb may be an insurance issue. Neither product should be treated as an unlimited coupon for a free HVAC upgrade.
How to Challenge a Denied or Underpaid Claim
A denial is not necessarily the end of the process, but your response should address the insurer’s stated reason rather than simply repeating that air conditioning is important.
- Request the denial or settlement explanation in writing.
- Ask the insurer to identify the exact policy language supporting its decision.
- Compare the adjuster’s findings with your contractor’s diagnosis.
- Submit missing photographs, reports, estimates, or maintenance records.
- Request a supervisor review or follow the policy’s appeal procedure.
- Ask whether reinspection, mediation, or appraisal is available.
- Contact your state insurance department when you believe the claim was handled unfairly.
Appraisal generally resolves disputes over the amount of a covered loss, not whether the policy provides coverage in the first place. Consumer regulators also recommend asking for written reasons, using the insurer’s appeal process, and contacting the state insurance department when a dispute remains unresolved.
Maintenance Records Can Strengthen Your Claim
Maintenance does not create coverage for an excluded loss, but good records can help rebut an allegation that neglect caused the failure. Keep receipts for seasonal inspections, refrigerant work, capacitor replacements, filter changes, coil cleaning, and previous repairs.
ENERGY STAR recommends checking filters regularly because dirty filters restrict airflow, make the system work harder, and can contribute to early equipment failure. A documented maintenance routine gives the insurer fewer reasons to blame a sudden loss on long-term neglect.
Experiences That Reveal What Makes an AC Claim Succeed
Experience One: The Lightning Claim With a Clear Timeline
Consider a homeowner whose air conditioner worked normally before an evening thunderstorm. During the storm, the lights flickered, the thermostat went blank, and several electronic devices stopped working. The homeowner photographed the thermostat, saved the utility outage notification, and called an HVAC company the following morning.
The technician documented electrical damage to the control board and compressor windings, stating that the failure pattern was consistent with a sudden surge. An electrician also found damage to a surge protector. The homeowner submitted both reports, photographs, the service history, and replacement estimates.
This type of claim has a coherent story. The system operated before a documented event, multiple devices were affected, professionals identified electrical damage, and the homeowner preserved evidence. After the deductible, the insurer may have a reasonable basis to cover repair or replacement under lightning, electrical-current, or equipment breakdown provisions.
Experience Two: The Old Compressor With No Covered Event
Now consider a different homeowner whose 18-year-old AC gradually became noisier and less effective. It required refrigerant twice, had visible corrosion, and had not received professional maintenance in several years. One afternoon, the compressor stopped running. There was no storm, fire, surge, impact, theft, or other identifiable event.
The homeowner files a claim because the replacement estimate is painfully large. Unfortunately, price alone does not turn a mechanical failure into insured damage. The technician’s report attributes the failure to age, refrigerant loss, and worn internal components. A standard homeowners policy would probably exclude the loss as wear and tear or deterioration.
The better financial options might include a home warranty claim, manufacturer warranty, contractor financing, energy-efficiency rebates, tax incentives, or an out-of-pocket replacement. Filing repeated small or clearly uncovered claims can also affect claim history, so checking the likely cause and deductible first is usually prudent.
Experience Three: The Hail Claim That Initially Looked Like Wear
In a third situation, an insurer initially concludes that a condenser’s bent fins are cosmetic and that compressor failure resulted from age. The homeowner does not respond with an angry 2 a.m. email written entirely in capital letters. Instead, the homeowner obtains a second HVAC evaluation.
The second technician maps fresh impact marks across the top and storm-facing side of the cabinet, documents damaged fan blades, and explains how the impact caused vibration and refrigerant-line damage. The homeowner supplies dated photographs from before the storm, local hail records, and a neighbor’s photograph showing hailstones beside the unit.
The homeowner then asks for reinspection and identifies the specific wind-and-hail provisions believed to apply. The new evidence does not guarantee payment, but it turns a vague disagreement into a technical coverage question supported by documentation.
The Shared Lesson
Successful air-conditioner claims are usually not built around clever wording. They are built around a covered cause, prompt reporting, consistent evidence, credible professional opinions, realistic estimates, and a policy that actually covers the event.
Unsuccessful claims often begin with an old unit, no identifiable incident, incomplete records, rushed permanent repairs, or an assumption that insurance should pay simply because replacement is expensive. Insurance is designed to transfer specified risksnot every unpleasant cost associated with owning a house.
Conclusion
To get home insurance to pay for an air conditioner, focus first on the cause of damage. A unit harmed by lightning, fire, hail, wind, vandalism, or another covered event may qualify. A unit that fails from age, corrosion, poor maintenance, or ordinary mechanical wear usually will not.
Review your policy, confirm the deductible, photograph the damage, obtain a detailed HVAC diagnosis, preserve replaced parts, report the loss promptly, and keep every receipt and communication. When a claim is denied, request the reason and policy language in writing, then respond with evidence rather than frustration.
The goal is not to “make” an insurer buy a new air conditioner. The goal is to demonstrate that a legitimate covered event damaged insured property and that the requested payment accurately reflects the covered loss. That approach is less dramatic than arguing with a claims representativebut far more likely to keep both your home and your claim from overheating.