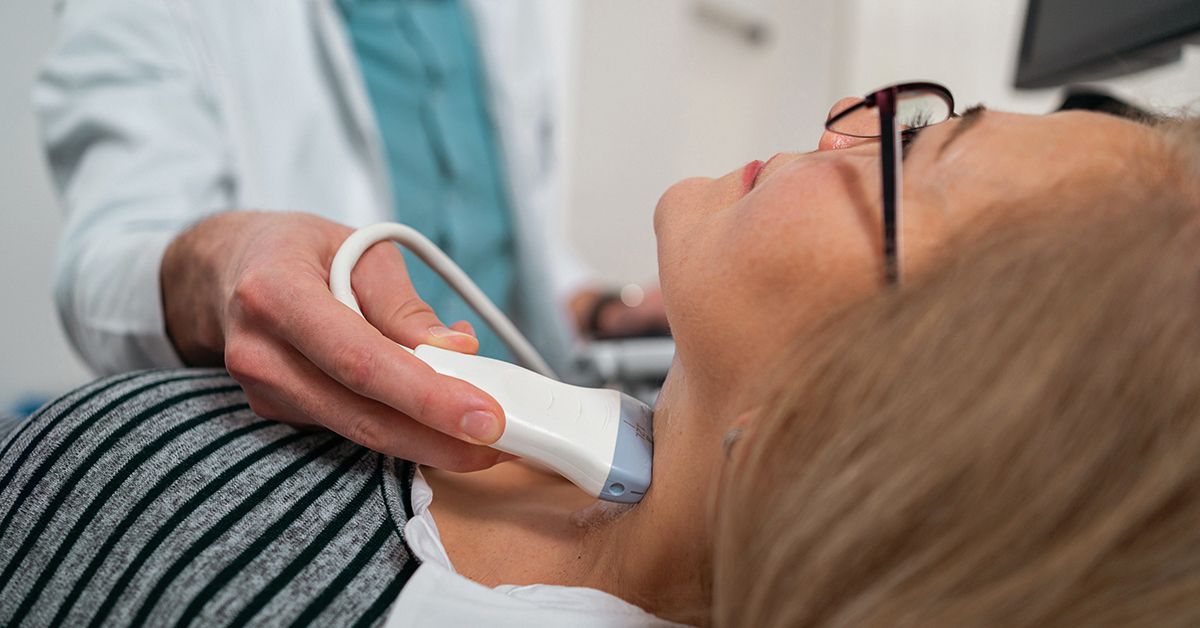
Ultrasounds have a pretty wholesome reputation in medicine. They do not involve radiation, they help doctors look at everything from blood flow to heart function, and they are often the imaging test that says, “Let’s investigate this without making things more dramatic than necessary.” But when it comes to Medicare coverage for ultrasounds, the real question is not whether ultrasound technology is useful. It absolutely is. The question is whether the scan is considered medically necessary, how it is billed, and which part of Medicare is on the hook for the cost.
That distinction matters. Under Medicare, an ultrasound is not automatically covered just because a doctor mentions it, a patient requests it, or a facility has a very persuasive scheduling department. Coverage usually depends on why the test is ordered, where it is performed, whether the provider participates in Medicare, and whether the documentation supports the claim. In other words, Medicare is not anti-ultrasound. It is anti-vague paperwork.
This guide breaks down what Medicare usually covers, what it may not cover, how costs work under Original Medicare and Medicare Advantage, and what beneficiaries commonly experience when they try to get an ultrasound approved and paid for.
Does Medicare cover ultrasounds?
Yes, Medicare often covers ultrasounds, but usually as diagnostic imaging, not as a casual “just checking” scan. In plain English, Medicare is most likely to pay when a doctor or other qualified provider orders the ultrasound to evaluate a symptom, confirm a diagnosis, monitor a known condition, or guide treatment.
That means an ultrasound can be covered when it is used to investigate problems such as abdominal pain, suspected gallbladder disease, leg swelling, abnormal blood flow, heart symptoms, a lump, or findings that need more detail after another imaging test. The fact that the machine uses sound waves is not what gets it covered. The medical reason for the test is what matters.
The simplest rule of thumb
If the ultrasound is ordered to diagnose or treat a medical problem, Medicare coverage is much more likely. If it is being used as a routine screening test without a covered screening benefit, or if the medical record does not clearly explain why the scan is needed, coverage becomes shakier.
Medicare also recognizes that not every ultrasound procedure is the same. Some ultrasound diagnostic procedures are generally covered, while experimental or unproven techniques may not be. So even within the ultrasound family, coverage can depend on the specific service being billed.
What Medicare usually covers
Most beneficiaries who ask about ultrasound coverage are really asking about diagnostic ultrasound under Medicare Part B. Part B generally covers outpatient diagnostic non-laboratory tests when the provider orders them to evaluate a condition. This is where many common ultrasounds live.
Common examples of ultrasounds Medicare may cover
Abdominal ultrasound: Often used for pain, suspected gallstones, liver issues, kidney problems, or a possible abdominal aortic aneurysm.
Pelvic ultrasound: May be ordered to investigate pain, bleeding, masses, or other concerning symptoms.
Vascular or duplex ultrasound: Commonly used to check circulation problems, narrowed arteries, venous insufficiency, or a possible blood clot.
Echocardiography: Cardiac ultrasound may be used when a patient has shortness of breath, a murmur, chest symptoms, suspected heart failure, valve disease, or another cardiac concern.
Breast ultrasound: Medicare is more likely to cover this when it is diagnostic, such as following up on a lump, dense tissue concerns, or an abnormal mammogram, rather than as a broad routine screening add-on for everyone.
In all of these cases, the key phrase is the same: medical necessity. Medicare is asking whether the test is reasonable and necessary for diagnosis or treatment, not whether it sounds like a good idea in a general sense.
How much does an ultrasound cost under Original Medicare?
Here is where the fine print starts doing cardio.
Under Original Medicare, outpatient diagnostic ultrasounds are usually handled under Part B. In 2026, the Part B deductible is $283. After that deductible is met, beneficiaries typically pay 20% of the Medicare-approved amount for covered services when the provider accepts assignment.
That is the clean version. The messier version is that your actual bill can still vary depending on where the ultrasound happens.
Doctor’s office or independent imaging center
If the ultrasound is performed in a doctor’s office or an independent diagnostic testing facility, the classic Part B model often applies: deductible first, then 20% coinsurance on the Medicare-approved amount.
Hospital outpatient department
If you get the test in a hospital outpatient setting, costs can be higher or at least more confusing. You may owe the Part B deductible plus a facility copayment, in addition to the professional component of the service. This is one reason two ultrasounds that seem identical on paper can produce very different bills.
Inpatient hospital stay
If the ultrasound is part of a formal inpatient hospital admission, the billing can shift because hospital care is generally covered through Part A, while some physician services may still be billed separately. Patients often assume “I stayed overnight” automatically means inpatient. Medicare does not. Observation status is still outpatient, and that distinction can affect what you owe.
Another important point: Original Medicare has no annual out-of-pocket maximum. So if you need repeated imaging, specialist visits, and follow-up care, those 20% coinsurance amounts can add up surprisingly fast.
When Medicare may not cover an ultrasound
Not every ultrasound gets the green light. Common reasons for noncoverage or claim trouble include:
No clear medical necessity
If the ordering provider does not document symptoms, abnormal findings, or a reasonable clinical purpose, Medicare may treat the scan as unnecessary.
Screening use without a covered screening benefit
Medicare covers many diagnostic ultrasounds, but it does not broadly cover every ultrasound as a preventive screening tool. If a patient wants a scan for reassurance rather than because of a documented medical reason, that is where coverage often falls apart.
Experimental technique
Some ultrasound procedures or methods may be considered experimental or not covered under Medicare policy. When that happens, the issue is not the diagnosis alone but the specific type of service being billed.
Missing or weak documentation
This is a major one. Claims can be denied because the medical record does not support the diagnosis code, the indication is too vague, records are incomplete, or the frequency of testing is not justified. Ultrasound claims are not uniquely cursed, but sonography documentation problems are common enough that they deserve their own warning label.
The big exception people should know: AAA screening ultrasound
There is one ultrasound that gets special preventive-service attention under Medicare: the abdominal aortic aneurysm, or AAA, screening ultrasound.
Medicare Part B covers a one-time screening ultrasound for eligible people who are at risk and have a referral from a doctor or other provider. This is not an unlimited benefit and not a “whenever you feel curious about your aorta” situation. It is a defined preventive service with specific eligibility rules.
Generally, the at-risk category includes people with a family history of abdominal aortic aneurysm and certain men ages 65 to 75 with a smoking history. If the provider accepts assignment, the beneficiary typically pays $0 for this covered screening.
That makes the AAA screening ultrasound unusual in the Medicare world: it is an ultrasound that can be covered as a preventive screening, not merely as diagnostic imaging after symptoms appear.
Original Medicare vs. Medicare Advantage for ultrasound coverage
Medicare Advantage plans must cover at least the services that Original Medicare covers. So if a diagnostic ultrasound is covered by Medicare, a Medicare Advantage plan generally has to cover it too.
But the path can feel very different.
With Original Medicare
You usually have more flexibility in choosing providers who accept Medicare, and prior authorization is less commonly part of the process for standard services. Your costs are typically driven by the Part B deductible, the 20% coinsurance, and whether the service was provided in a higher-cost outpatient setting.
With Medicare Advantage
Your plan may require network providers, referrals, or prior authorization for certain imaging services. The scan may still be covered, but the administrative steps can be more plan-specific. Cost-sharing also varies. One plan might charge a flat copay for imaging, while another may use coinsurance. So the question is not just “Does Medicare cover this?” but also “How does my plan cover this?”
If you have Medicare Advantage, always check the plan’s Evidence of Coverage, provider network, and prior authorization rules before the appointment if possible.
How Medigap can help
If you have Original Medicare plus Medigap, your supplemental policy may cover some or all of the out-of-pocket costs that Medicare leaves behind, including Part B coinsurance for a covered ultrasound. This can make a big difference for beneficiaries who need repeat imaging or who use hospital outpatient departments where charges feel less like a bill and more like a personality test.
Medigap does not create coverage for a service Medicare excludes. But if Medicare approves the ultrasound, Medigap may reduce what you personally owe.
How to avoid surprise bills for an ultrasound
Medicare billing gets easier when you ask a few practical questions before the appointment instead of after the Explanation of Benefits has already ruined your afternoon.
Ask why the ultrasound is being ordered
The reason should be specific. “To evaluate persistent right upper abdominal pain” is much better than “just checking.”
Confirm where the test will be performed
A hospital-owned outpatient department can cost more than a freestanding imaging center. Same scan, same body, very different billing energy.
Check whether the provider accepts Medicare assignment
This matters under Original Medicare because it affects how much you may owe beyond the standard cost-sharing rules.
Ask whether prior authorization is required
This is especially important for Medicare Advantage enrollees.
Watch for an ABN
If your provider thinks Medicare may not pay, you may be asked to sign an Advance Beneficiary Notice of Non-coverage. Do not treat this like random front-desk paperwork. Read it. It explains why Medicare might deny the claim and estimates what you may owe.
Review your Medicare Summary Notice
If the claim is denied, do not panic and do not assume the denial is the last word. Sometimes the issue is bad coding, incomplete documentation, or a billing error. The Medicare Summary Notice explains what was billed, what Medicare paid, and how to appeal if needed.
Examples of when coverage is likely and when it is not
Likely covered: A doctor orders a venous ultrasound because you have one swollen leg, pain, and concern for a blood clot.
Likely covered: Your cardiologist orders an echocardiogram after new shortness of breath and a heart murmur.
Likely covered: Your doctor orders a breast ultrasound after a mammogram shows an abnormal area that needs more evaluation.
Possibly not covered: You want a whole-body or targeted ultrasound for reassurance even though you have no symptoms, no abnormal findings, and no covered screening indication.
Possibly denied: The ultrasound itself is reasonable, but the diagnosis code or chart note does not explain medical necessity well enough for Medicare or the plan to approve payment.
Experiences people commonly have with Medicare coverage for ultrasounds
Many beneficiaries have a surprisingly similar experience with Medicare and ultrasounds, even when the medical reason is different. It often starts with a symptom that seems small enough to ignore but annoying enough to mention at an appointment: swelling in a leg, belly pain after meals, a new lump, shortness of breath, or a strange ache that refuses to mind its own business. The provider orders an ultrasound, and the patient leaves thinking, “Great, that sounds simple.” Medically, it often is. Financially, that is where the plot thickens.
One very common experience is that the test is covered, but not free. People hear that Medicare covers diagnostic imaging and assume the bill will be tiny or nonexistent. Then the claim processes under Part B, and they discover they still owe the deductible or 20% coinsurance. The scan was covered. Their wallet simply did not feel the victory.
Another frequent experience is confusion about where the test took place. Someone may go to what feels like a normal clinic, only to later learn it was billed as a hospital outpatient department. That can mean a different cost structure, separate facility charges, and a strong emotional desire to ask why the building looked so ordinary if the bill was going to act so fancy.
Patients with Medicare Advantage often describe a different sort of headache. The issue is not always whether the ultrasound is medically appropriate. It is whether the plan wants prior authorization, whether the imaging center is in network, and whether the ordering doctor used the right process. In those cases, the medical need may be obvious, but the administrative maze still has to be completed before the plan plays nicely.
People with Medigap often report a smoother financial experience. They may still go through the same medical process, but once Medicare approves the claim, the supplemental policy absorbs much of the leftover cost. This does not make the system charming, exactly, but it does make it less likely that a medically necessary ultrasound turns into a budgeting event.
Another pattern is that denials do not always mean the service was inappropriate. Sometimes the documentation was thin, the diagnosis code was too vague, or the claim was missing the detail Medicare expected. Beneficiaries often learn that an initial denial can sometimes be fixed by resubmitting the claim with better records or appealing through the Medicare process. The emotional arc is usually annoyance first, paperwork second, relief third.
There is also a noticeable difference between people who ask questions in advance and people who do not. Beneficiaries who confirm medical necessity, location, network status, assignment, and possible prior authorization tend to avoid more billing surprises. The test itself may be identical, but the experience feels far less chaotic.
In the end, the most relatable Medicare ultrasound experience is this: the technology is modern, fast, and efficient, while the billing process can feel like it was raised by a filing cabinet. The good news is that coverage is often available when the scan is truly needed. The better news is that a little preparation can keep a necessary ultrasound from becoming an unnecessary financial mystery.
Final takeaway
Medicare does cover many ultrasounds, especially when they are ordered as medically necessary diagnostic tests. Under Original Medicare, that usually means Part B coverage for outpatient imaging, with the deductible and coinsurance rules applying. A key exception is the one-time AAA screening ultrasound for eligible at-risk beneficiaries, which can be covered as a preventive service.
The biggest reasons patients run into trouble are not usually because ultrasound is excluded altogether. The trouble tends to come from documentation, setting, coding, network rules, prior authorization, or confusion about cost-sharing. So if you remember only one thing, make it this: for Medicare, the question is not merely “Do you cover ultrasounds?” It is “Why is this ultrasound being done, how is it billed, and does the paperwork support it?”
Get those answers lined up, and Medicare coverage becomes much easier to understand. Ignore them, and even a harmless sound-wave test can arrive with a bill that sounds louder than the machine ever did.